Did the Incentive Actually Pay Off?
Evaluate data-center incentives by comparing promised public benefits with delivered investment, permanent jobs, payroll, tax revenue and infrastructure costs.
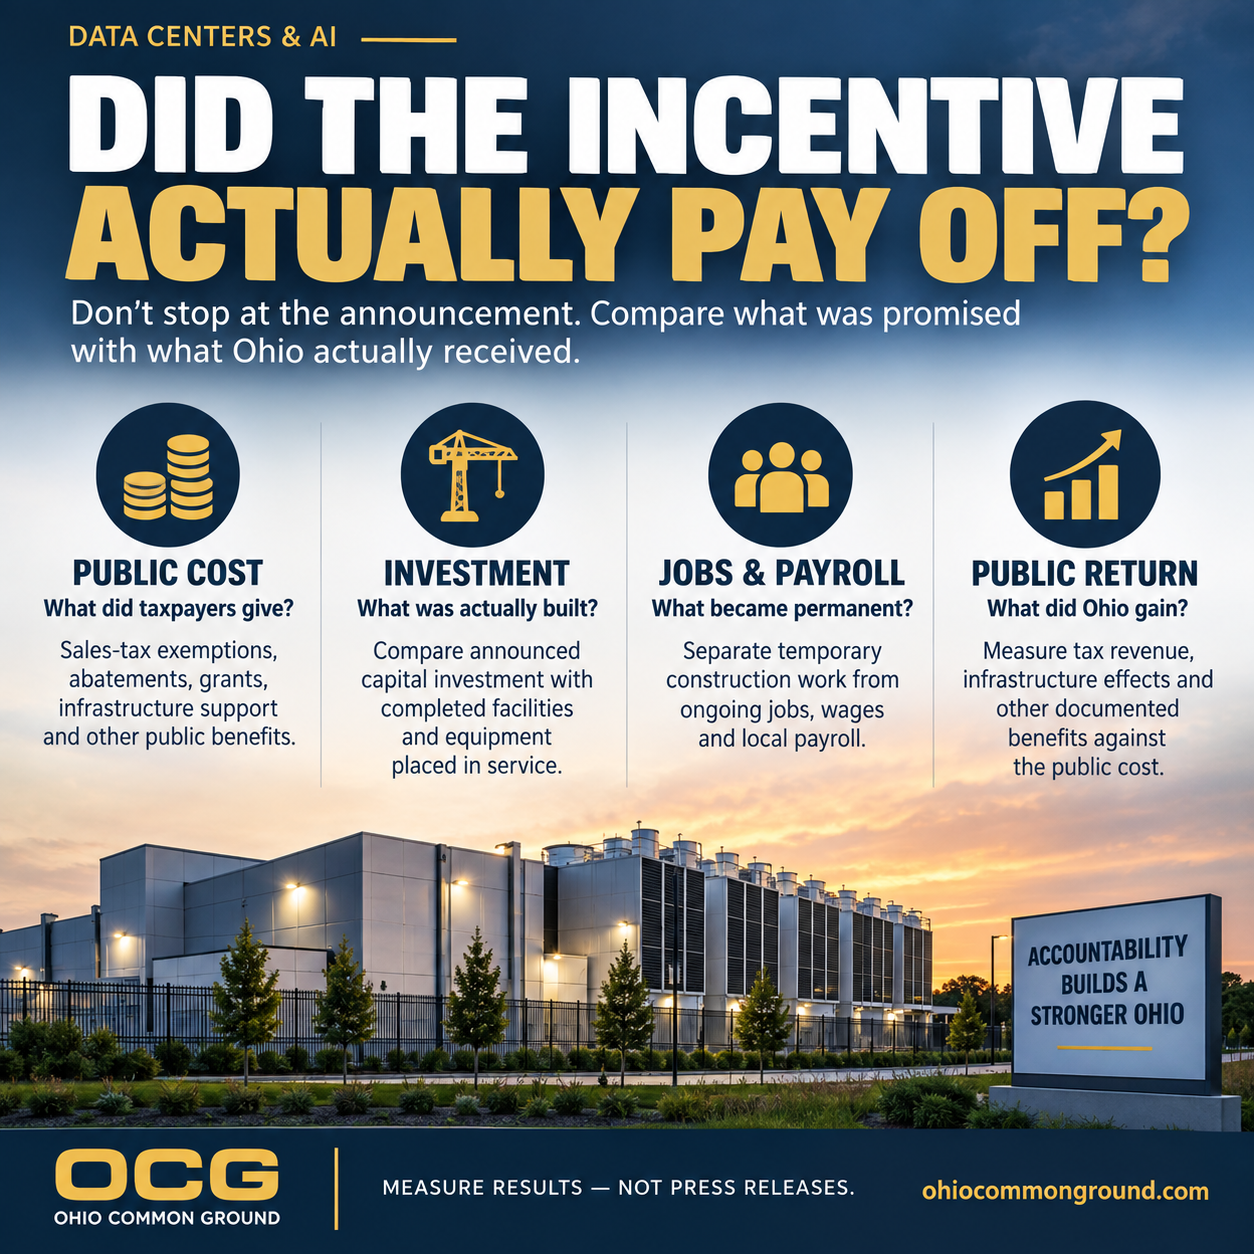
What This Graphic Shows
Economic-development incentives are usually announced before anyone knows whether the promised benefits will actually materialize. A useful accountability system therefore needs two columns: what was promised and what was delivered.
Start with the public cost. For data centers, that can include state sales-and-use tax exemptions, local property-tax arrangements, grants, publicly supported infrastructure or other negotiated benefits. These different incentives should not be collapsed into one number unless their values are calculated on a consistent basis.
Then measure the promised private investment against what was actually placed in service. Large headline investment figures can cover multiple phases or many years, so the relevant questions include how much construction was completed, how much qualifying equipment was installed and whether later phases occurred as announced.
Jobs require the same discipline. Separate temporary construction employment from permanent operating jobs, and track payroll or wages where those were part of the incentive agreement. Ohio's data-center exemption statute provides for agreements containing investment and payroll-related terms and includes reporting and certification mechanisms.
Finally, evaluate the broader public return: tax revenue actually received, infrastructure costs incurred, utility or transportation investments, and other measurable community benefits or burdens. The appropriate measure depends on what government officials said the incentive was intended to accomplish.
The principle is simple: an incentive should be evaluated against its own promises. Announced investment is not completed investment; construction jobs are not permanent jobs; and a large private project does not automatically establish that a public subsidy produced a positive return.
Key Takeaway
Measure results, not announcements. Compare the public cost of an incentive with the investment, permanent employment, payroll, tax revenue and other benefits actually delivered.
Verification Status:
Verified — Current
Last Verified:
September 15, 2026
Sources
Review the sources used to support this visual.
Ohio Revised Code Section 122.175 — Tax exemption for computer data center equipment
Explore More
Continue exploring the issue or return to the complete OCG Visual Library.