How Do Ohio Tax Reduction Factors Work?
Ohio's tax-reduction-factor system can lower effective rates on qualifying levies when carryover property values rise.
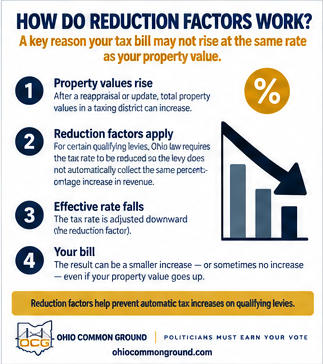
What This Graphic Shows
Under ORC 319.301, the tax commissioner determines reduction percentages for qualifying taxes on carryover property. The purpose is to reduce the sums levied so that qualifying taxes do not automatically collect the same percentage increase in revenue merely because existing property values increased.
The statute contains important exceptions, including certain specified-dollar levies, taxes within the constitutional one-percent limitation, and certain municipal-charter taxes.
Key Takeaway
Reduction factors can prevent automatic revenue growth on qualifying levies, but they do not apply to every part of a tax bill.
Verification Status:
Last Verified:
September 18, 2026
Sources
Review the sources used to support this visual.
Explore More
Continue exploring the issue or return to the complete OCG Visual Library.