The Property-Tax Relief Toolbox: Different Tools, Different Trade-Offs
Property-tax reform can use exemptions, credits, caps, circuit breakers, levy changes or replacement revenue, and each tool changes different parts of the system.
What This Graphic Shows
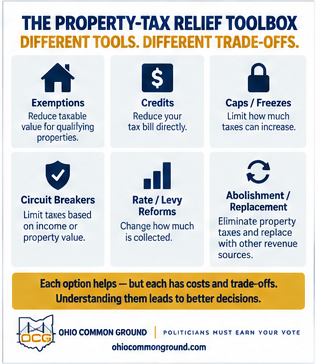
Property-tax relief is not one policy. Exemptions change the taxable base for qualifying property; credits reduce tax liability; caps or freezes limit specified changes; circuit breakers target burdens using a formula; levy reforms change how revenue is authorized or collected; and abolition/replacement removes property-tax revenue and requires another funding approach.
Each option has different distributional, fiscal and administrative effects. Comparing tools requires asking who qualifies, who pays, which governments lose revenue, and how any lost revenue is replaced.
Key Takeaway
Different relief tools solve different problems and create different fiscal and distributional trade-offs.
Verification Status:
Last Verified:
September 18, 2026
Sources
Review the sources used to support this visual.
Explore More
Continue exploring the issue or return to the complete OCG Visual Library.